Retired couple in hiking gear at a Grand Canyon viewpoint

Who we work with

We work with two groups:  

  • Retirees (typically 60–75) who want to ensure their savings generate reliable, protected income for the rest of their lives.
  • Pre-retirees (typically 50–62) who are 5–10 years from retirement and want to start positioning a portion of their savings into a more protected structure before they need to draw on it.

How we work

We begin with a free, no-obligation retirement income review. We look at what you have, what you need, and the gap between them. We then present options — clearly, without jargon — and let you decide at your own pace.

We are independent advisers working with multiple insurance carriers, which means we recommend what is right for you, not what generates the highest commission.

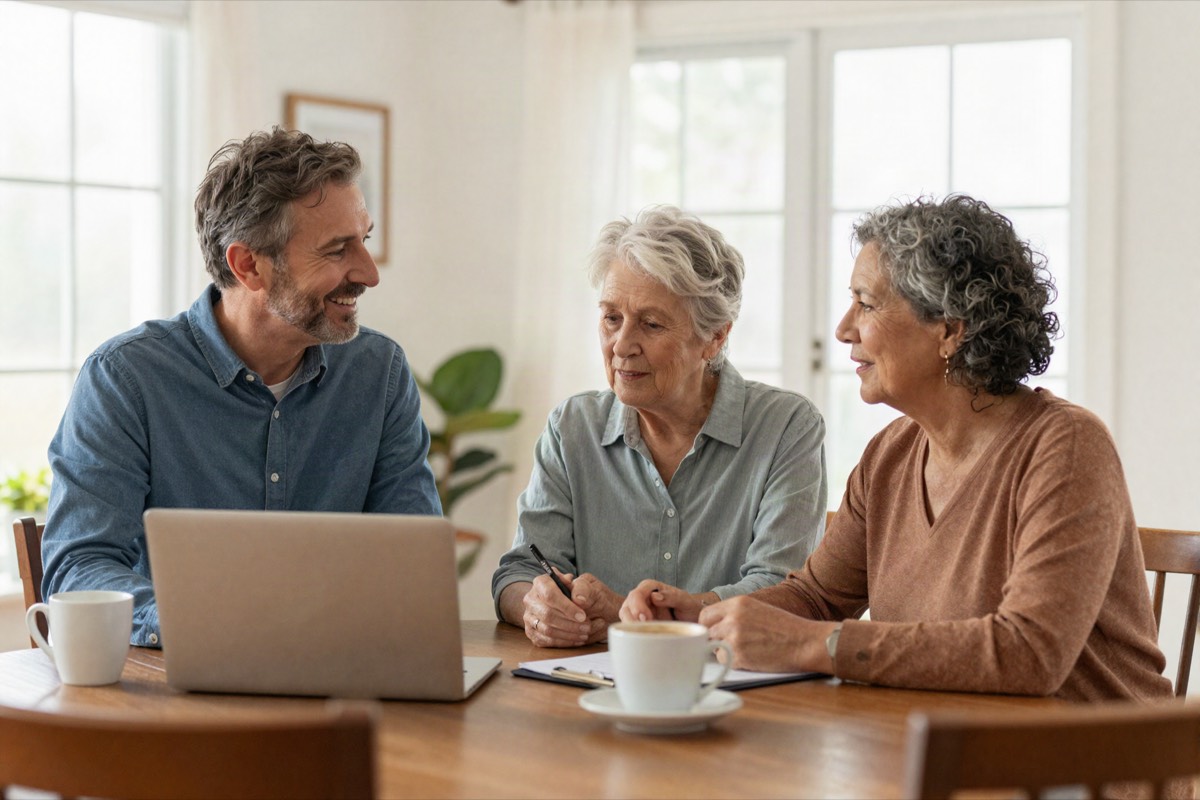
Financial adviser talking through retirement income options with clients at their dining table

FAQs

What is a Fixed Index Annuity?

A Fixed Index Annuity (FIA) is a contract with an insurance company that lets your money grow based on the performance of a market index — such as the S&P 500 — while protecting you from market losses. When the market goes up, you receive a portion of that growth. When the market goes down, your account value does not go down. Many FIAs also include an optional income rider that guarantees income for life, regardless of how long you live or what the market does.

Is a Fixed Index Annuity the same as a variable annuity?

No. A variable annuity invests directly in sub-accounts similar to mutual funds, meaning your account value can decline in a down market. A Fixed Index Annuity does not invest directly in the market — your principal is protected from market losses. Growth is linked to an index, but you are not directly exposed to market risk.

Can I lose money in a Fixed Index Annuity?

Your principal is protected from market losses. However, FIAs are not FDIC-insured bank accounts. Their guarantees are backed by the financial strength of the issuing insurance company, which is why we only work with highly-rated carriers. Early withdrawals during the surrender period may incur a charge.

What is a guaranteed income rider?

A guaranteed income rider is an optional feature — added to an FIA for an additional annual fee (typically 0.95%–1.25%) — that guarantees a specific level of monthly or annual income for the rest of your life, regardless of market performance or how long you live. It effectively creates a personal pension from your savings.

How much money do I need to use a Fixed Index Annuity?

Most FIA contracts have a minimum premium of $20,000–$50,000. They work best as part of a broader retirement income strategy — typically allocated to money you want to protect and use for predictable income, rather than funds you may need liquid access to in the short term.

Fixed Index Annuities are insurance products, not securities. They are not FDIC-insured, not bank-guaranteed, and may lose value only if surrendered early. Guarantees are backed by the issuing insurer's claims-paying ability. [State insurance licensing disclosures.]